Why the renewal application deserves more than a rubber stamp
It is easy to treat a renewal as an administrative step — confirm the limits look similar, sign, move on. That approach works fine in a year with no operational change and quietly fails in a year with several small ones, because most storefront businesses accumulate change gradually: a bit more stock, a slightly different staffing pattern, a new delivery arrangement. None of those individually feels renewal-worthy, but together they can leave the policy describing a business that no longer exists.
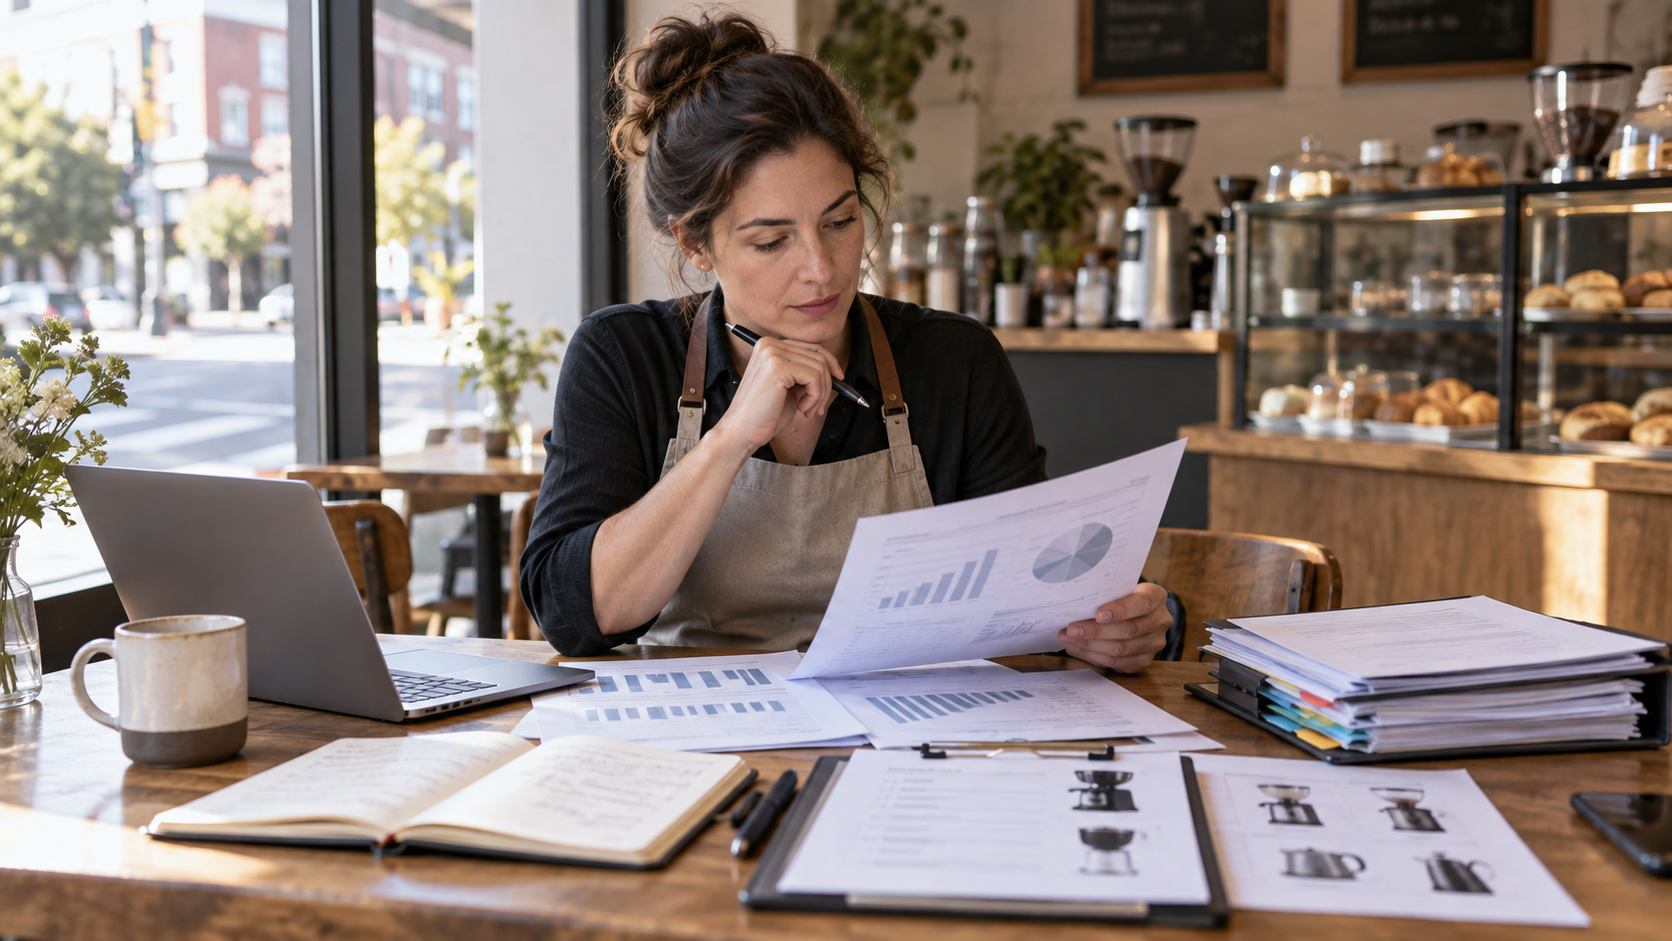
A useful renewal starts from the business as it actually operates right now, cross-checked against last year’s application, rather than starting from last year’s application and assuming nothing changed. That reversal of order — current facts first, prior submission second — catches gaps the other order tends to miss.
Begin well before the expiration date
Collect the current declarations, all forms and endorsements, any loss information available from the carrier, current lease insurance requirements, and a running list of operational changes that happened during the policy term. Starting this thirty to sixty days before expiration — rather than the week the renewal notice arrives — leaves time to resolve a gap instead of accepting a rushed quote. California Insurance Code section 678.1 already gives a commercial policyholder a head start on this timeline: an insurer must give at least 60 days’, and no more than 120 days’, notice before nonrenewing a policy, or before conditioning renewal on reduced coverage, a higher deductible, or a rate increase of more than 25 percent. That notice, once it arrives, is the latest possible moment to start this review, not the first.
For a San Francisco storefront, this window also allows time to request updated loss history from the outgoing carrier, which some carriers take longer to produce than owners expect. A clean loss history, documented and available early, tends to produce a more competitive renewal.
Update the account facts before comparing anything
Compare prior revenue and payroll estimates against current results. List new locations, added delivery or catering activity, online fulfillment, new equipment, additional storage, or any change in the products sold or food served. A revenue increase alone is not necessarily a problem, but an increase that was never disclosed can look, in hindsight, like an inaccurate submission.
Pay particular attention to stock values at seasonal peaks rather than an annual average — a boutique or specialty grocer on a corridor like Fillmore Street often carries meaningfully higher inventory during a holiday season or a neighborhood event weekend than the rest of the year, and a property limit built around an average value can fall short exactly when it matters most.
- Current revenue and payroll compared to the prior submission
- New locations, delivery, catering, or online fulfillment added during the term
- Equipment purchased, leased, or retired during the term
- Seasonal stock peaks, not just an annual average value
Put documents side by side instead of trusting a summary
Compare key lease or vendor insurance requirements directly against proposed limits, deductibles, scheduled locations, and endorsements. Flag any difference explicitly rather than assuming a policy heading — "commercial property," "general liability" — means a specific lease requirement is automatically satisfied.
This is also the point to compare property valuation methods across renewal quotes. Replacement cost and actual cash value produce very different outcomes after a loss, and a renewal that quietly shifted valuation basis to keep the premium flat is a change worth catching before, not after, a claim.
Create a decision record that survives to next year
Save the comparison, the forms actually reviewed, the questions raised during the process, and the final issued documents together, dated. This record becomes the starting point for next year’s renewal, which turns an annual scramble into a shorter, more accurate process each time it repeats.
Policy wording, declarations, and endorsements control what the renewed policy actually covers.
Decision checklist for your coverage review
Use these questions with your current policy, lease or contract, and business records. They help identify facts and terms to raise before requesting or comparing insurance options.
- What changed in revenue, payroll, stock, or equipment since the last renewal?
- Which locations and off-site activities need to be added to the schedule?
- What lease or vendor insurance requirements still apply, and are they met?
- Who keeps the final proposal comparison, and where is it stored?
- Does the property valuation basis match what was used at the prior renewal?
- Are seasonal stock peaks reflected in the property limit, not just an annual average?
Keep the review useful after the meeting
Set the current declarations, endorsements, relevant lease or venue agreement, and latest business records beside this guide. Record the date, the business change, the form reviewed, and unanswered questions. That makes the next renewal, certificate request, or opening decision easier to revisit.
Fillmore Risk can prepare the submission and compare available terms against the storefront or food-service operation. The issued policy documents remain controlling: policy wording, declarations, and endorsements control.