Commercial coverage for storefronts

Insurance for your property and your ability to trade.

We compare property and liability cover alongside business income insurance. The result shows which part of the operation each policy addresses and the limitations attached to it.

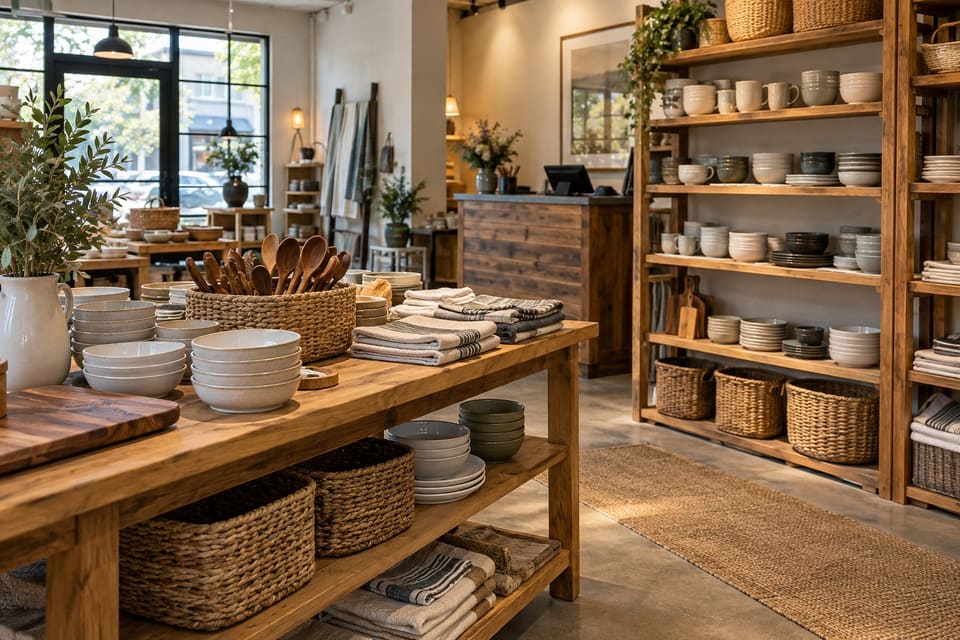
Daylight falling across ceramics, baskets and linens in a shop interior.

The things that let you trade

Commercial property

We seek property insurance for the stock, equipment, and improvements you would need to replace after covered damage.

We work through who owns or must insure each part of the fit-out. The resulting property schedule distinguishes your equipment and improvements from items belonging to the landlord or an equipment lessor.

Terms we compare

  • Stock values at busy periods, not only on the renewal date
  • The valuation basis for equipment and tenant improvements
  • Responsibility for glass, signs, and alterations under the lease
  • Separate treatment of flood, earthquake, or equipment breakdown
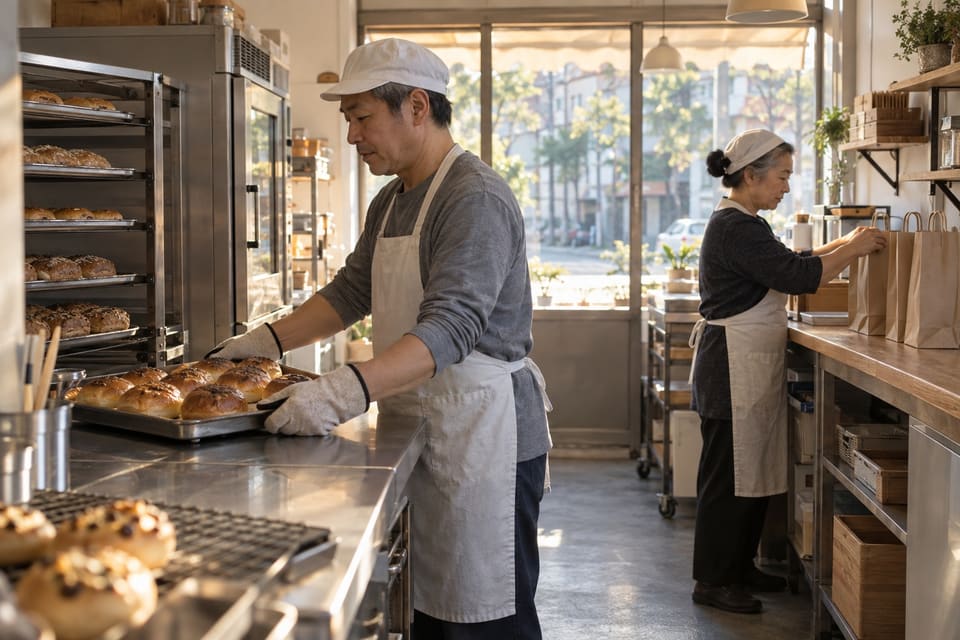
Two adults preparing bread trays and paper bags in a bakery before opening.

The public side of the premises

General liability

We compare general liability for customer injury and damage to other people’s property arising from your retail or food-service operation.

We describe your customer-facing activities to the market, including seated dining, tastings, or deliveries. We then check for exclusions that could restrict coverage for those activities.

Terms we compare

  • Premises and operations described in the submission
  • Product-related allegations and any restrictive endorsements
  • The lease’s additional-insured request and the actual policy wording
  • Activities that need a separate discussion, including alcohol service or deliveries
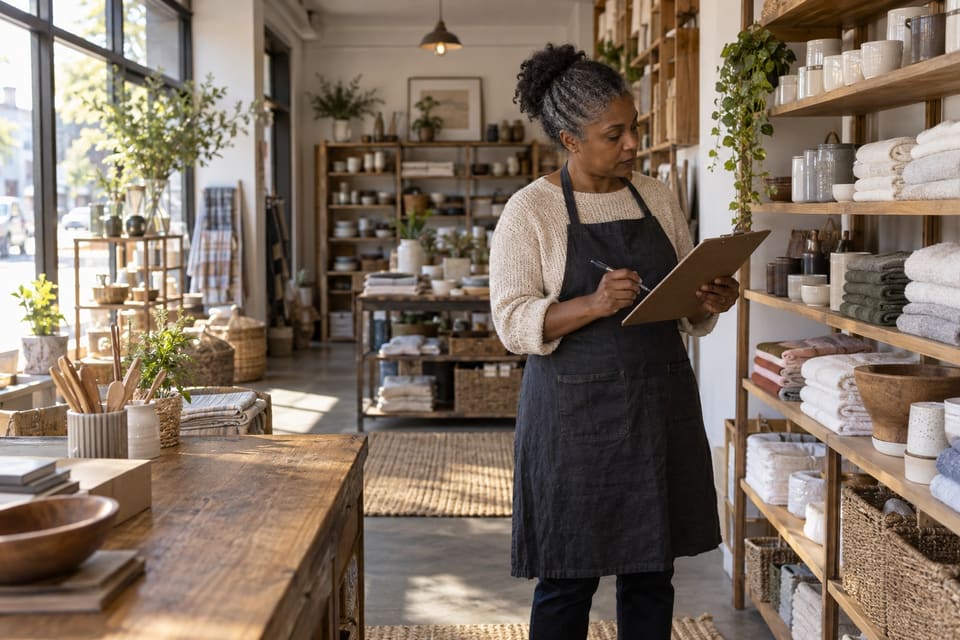
A woman checking stock beside shelves of towels and ceramics in a shop.

The time between closing and reopening

Business interruption

We help assess your business income exposure and compare insurance for revenue and continuing expenses after a covered interruption.

Reopening takes more than replacing damaged property. We compare the event that triggers income coverage, the waiting period, and the time allowed for restoration, including any extra expense provision for keeping work going.

Terms we compare

  • The property-damage trigger required by the wording
  • The limit and time available for the restoration period
  • Sales records, continuing expenses, and seasonal patterns
  • Any extension for utility interruption or income after reopening

For each proposal, we explain the insured events, valuation terms, and limits that would determine the policy response.