From window display to stockroom
Retail shops
We arrange commercial insurance for retail stock and fixtures, customer liability, and business income after covered damage.
Review retail shops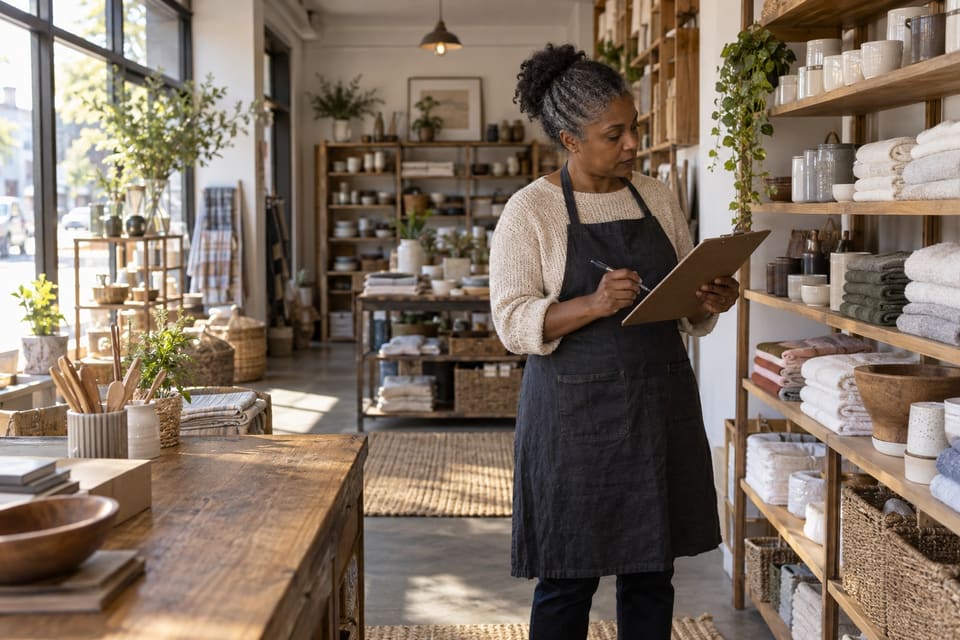
Commercial insurance · San Francisco
You run the shop or kitchen. We take the insurance account to market, follow up on the quotes, and explain what each policy would cover, from your stock and equipment to income lost after covered damage.

Lease and property coverage
We read the lease requirements, identify the property you are responsible for, and seek coverage for the fit-out and income your business depends on.
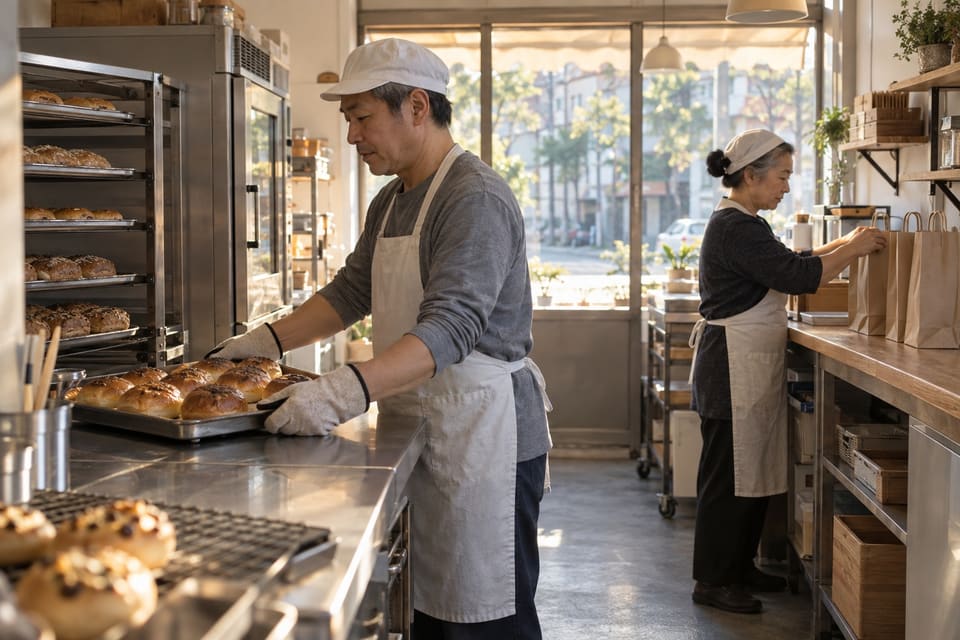
We separate the landlord’s building from your counters, kitchen equipment, and improvements, so the submission identifies the property you actually need to insure.
A shut storefront still owes rent and wages. We check the covered causes, waiting period, and restoration terms behind the business income figures you are quoted.
New stock levels, added equipment, and new food-service activity change the account. We update it as those happen rather than discovering them at renewal.
Commercial insurance options
We show how property, liability, and business income policies address a storefront loss, including the conditions that can limit a claim.
Choose a policy to read about
We seek property insurance for the stock, equipment, and improvements you would need to replace after covered damage.
What we check in the quotes
We compare general liability for customer injury and damage to other people’s property arising from your retail or food-service operation.
What we check in the quotes
We help assess your business income exposure and compare insurance for revenue and continuing expenses after a covered interruption.
What we check in the quotes
How we arrange your insurance
You explain how the business runs. We organize the submission and work through the market responses.
We ask about your stock and service, identify the equipment you rely on, and establish the deadline for a decision.
We prepare a submission from the business details and lease requirements, then handle questions and follow-up with the market.
We compare the terms and recommend an option, explaining how deductibles, exclusions, and business income conditions affect the choice.
Tell us what you sell or serve and when coverage needs attention. We will work through the account and the options available.
Businesses we work with
We build each submission around the operation, whether it depends on seasonal stock or refrigeration and daily service.
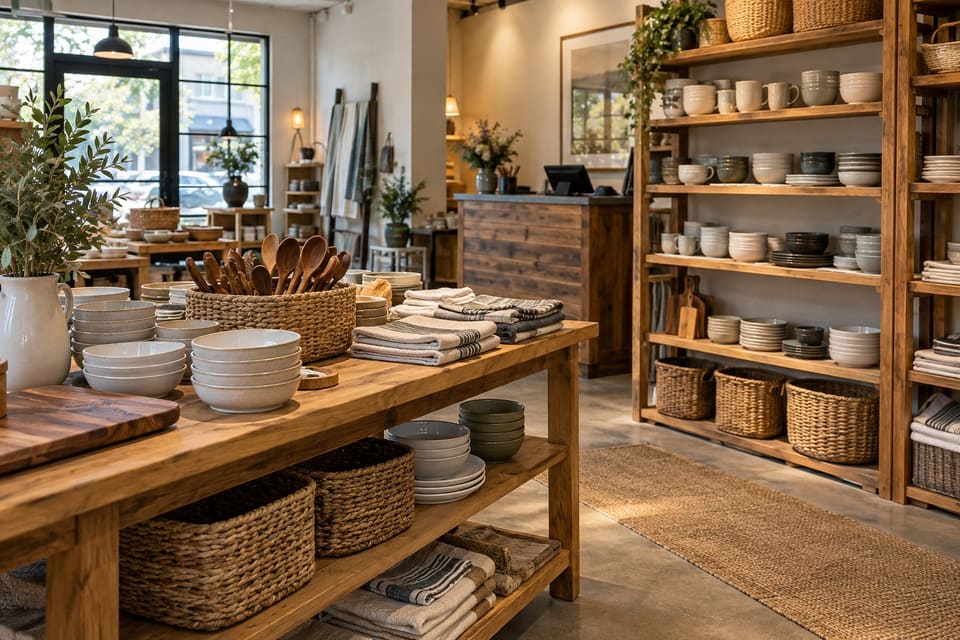
From window display to stockroom
We arrange commercial insurance for retail stock and fixtures, customer liability, and business income after covered damage.
Review retail shopsFrom prep to the last order
We shop insurance for cafés, kitchens, and food-service operators, with attention to cooking equipment, perishables, and customer liability.
Review food-service businessesThe policy behind the price
A low premium can come with restrictive valuation or income terms. We read the forms and endorsements, compare them with the lease, and tell you where the differences matter.
Fillmore Street
A San Francisco shop may keep seasonal orders in a separate unit. A café may prepare food away from the counter. We include those spaces in the account and check how proposed policies treat property and activity at each location. The insurance submission should follow your stock and equipment beyond the customer-facing address.
Before the next renewal
Learn how landlord requirements, inventory values, and business income terms affect the insurance we compare for your shop.
The landlord’s policy may not cover the fit-out or equipment you own or must insure. We use the lease to identify your responsibilities, then seek property terms for your stock and improvements, including rented equipment.
No. The wording usually needs a covered property-damage event before income coverage responds. The cause of the closure, waiting period, insured location, exclusions, and any extensions matter. Reduced foot traffic by itself is not the same as an insured loss.
We use your purchasing and sales patterns to assess peak stock values. We then compare the proposed limit and any seasonal increase against those peaks so an annual average does not hide your busiest inventory period.