Why the operating description carries more weight than the business name
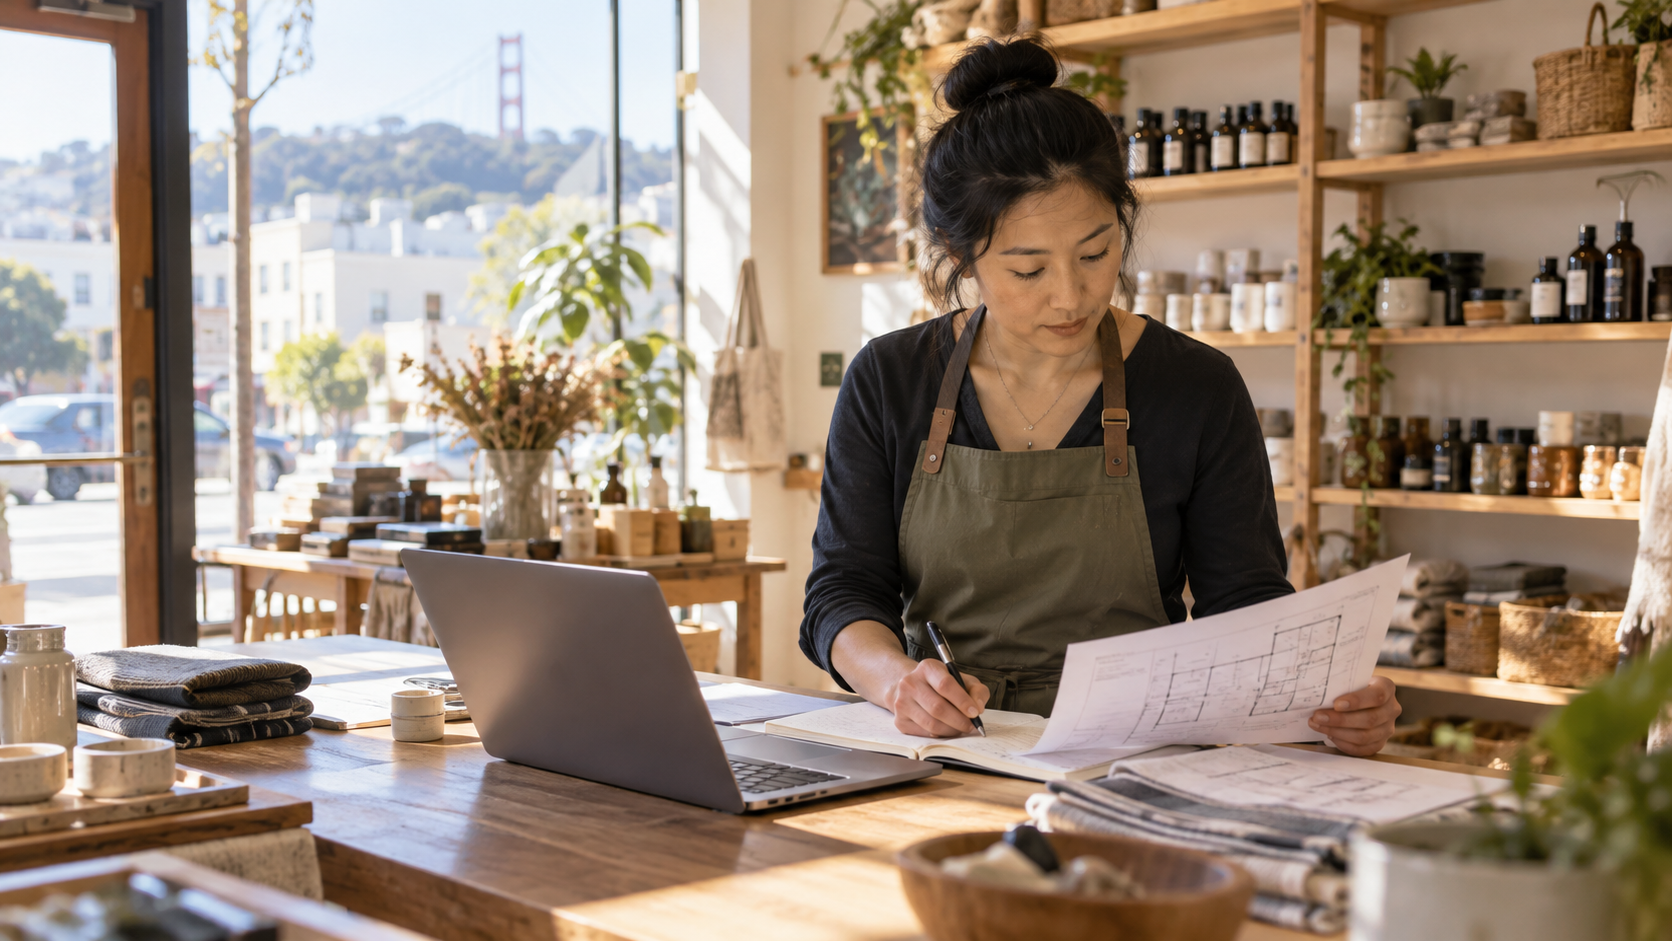
Every retail or food-service insurance submission opens with a short business description, and that description does more work than most owners expect. A market reviewing a San Francisco storefront account is not underwriting the shop’s name or its Fillmore Street address by itself; it is underwriting the activity behind the counter — what is sold, how it is served, who handles it, and where the property actually sits. Two shops on the same block can carry very different exposures even when their signage looks similar.
Retail insurance and food-service insurance in San Francisco both start from this description, because it shapes the classification code, the property schedule, and the exclusions that follow. California Insurance Code section 331 makes concealment of a material fact grounds for the insurer to rescind the entire policy — and it applies whether or not the omission was intentional. An outdated description is not just a paperwork gap; it is the exact fact pattern that provision addresses. Keeping the description current is far cheaper than contesting a rescission after a loss.
When the description needs an update
A move, a new product line, added cooking, a delivery service, off-site events, or online fulfillment can each make last year’s description incomplete. The question is not whether the brand changed; it is whether the operation changed. A boutique that starts alterations on-site, a café that adds a beer and wine license, or a shop that starts warehousing seasonal stock in a second unit have all changed the facts an insurer is pricing, even if the storefront looks the same from the sidewalk.
San Francisco retail and food-service businesses tend to accumulate these small changes gradually — a pop-up table added for a neighborhood street fair, a second point-of-sale system for online orders, a walk-in cooler installed where dry storage used to be. None of these individually feels like a reason to call the broker. Together, over a policy term, they can add up to an operation that no longer matches the submission on file.
Gather the operating facts before writing anything down
Before drafting a new description, collect the facts rather than the marketing language. List what is sold or served, how customers use the space, peak inventory levels, the equipment relied on daily, where stock and supplies are stored, and any work performed away from the address. Separate regular, ongoing activity from an occasional event — a monthly pop-up is a different fact pattern than a weekly delivery route.
For a food-service operation, note cooking methods, refrigeration dependency, seating capacity, and whether alcohol is served. For a retail shop, note seasonal buying patterns, consignment or held inventory that belongs to someone else, and any services performed for customers beyond selling a product — gift wrapping is usually incidental, but alterations, repairs, or styling consultations are a different question.
- Customer access, seating, and hours of operation
- Stock levels at seasonal peaks, not just on renewal day
- Food preparation, delivery, or catering performed off-site
- Equipment owned, leased, and rented, and who is responsible for each
Compare the terms that actually follow the description
Once the facts are organized, read the classification, scheduled locations, exclusions, and endorsements on the current or proposed policy beside the description that was supplied. A short declaration-page label — "retail store" or "restaurant" — does not explain every activity a business performs, and it is the underlying description, not the label, that controls how a claim is evaluated.
This is also the point to flag anything that reads like a mismatch: a policy written for a business without on-site food preparation when the shop has since added a small kitchen, or a location schedule that omits a storage unit that now holds a meaningful share of inventory. Raising the mismatch before a loss is a documentation exercise. Raising it after a loss is a coverage dispute.
Keep a dated record and revisit it before it goes stale
Save the description alongside the lease, equipment list, vendor agreements, and the final proposal comparison, and date the file. When a new activity starts — delivery, a seasonal menu addition, a new storage location — raise it before it becomes routine rather than waiting for the renewal date to surface it.
This habit matters more for San Francisco storefronts than the paperwork suggests. Rents on corridors like Fillmore Street push owners to use every square foot of a small space efficiently, which means operations change faster than in a larger suburban footprint. A dated, specific operating description is one of the more useful documents an owner can hand a broker at renewal, and it is far more useful than a verbal summary of "business as usual." Policy wording, declarations, and endorsements control what is actually covered.
Decision checklist for your coverage review
Use these questions with your current policy, lease or contract, and business records. They help identify facts and terms to raise before requesting or comparing insurance options.
- What does the business sell, serve, or make today?
- Where are stock, equipment, and prep work located?
- Which activities happen off-site or after normal hours?
- What changed since the last submission — new products, services, or locations?
- Does the classification on the declarations page match the current activity?
- Who is responsible for equipment that is leased or rented rather than owned?
Keep the review useful after the meeting
Set the current declarations, endorsements, relevant lease or venue agreement, and latest business records beside this guide. Record the date, the business change, the form reviewed, and unanswered questions. That makes the next renewal, certificate request, or opening decision easier to revisit.
Fillmore Risk can prepare the submission and compare available terms against the storefront or food-service operation. The issued policy documents remain controlling: policy wording, declarations, and endorsements control.